State: Required
Minnesota: The Rules Your Auto Policy Must Follow
Minnesota is a no-fault state. Every policy must carry liability, personal injury protection, and both uninsured and underinsured motorist coverage, and the law limits when an insurer can cancel or refuse to renew. Here is what that means for your policy.
By PolicyBrook Editorial Team Updated 6-minute read
Declarations
Minnesota- UM/UIM rule
- Required
- Minimum liability
- 30/60/10
- Insurer cancellation notice
- 30 days (10 nonpayment)
- Nonrenewal notice
- 60 days
In brief
A Minnesota policy must carry at least $30,000/$60,000/$10,000 of liability coverage, $40,000 of no-fault personal injury protection per person, and separate uninsured and underinsured motorist coverages of at least $25,000/$50,000 each, which you cannot waive. Once a policy has been in force 60 days, an insurer can cancel only for reasons the statute lists, with 30 days' notice (10 for nonpayment), and it must give 60 days' notice before it refuses to renew. The Minnesota Department of Commerce enforces these rules.
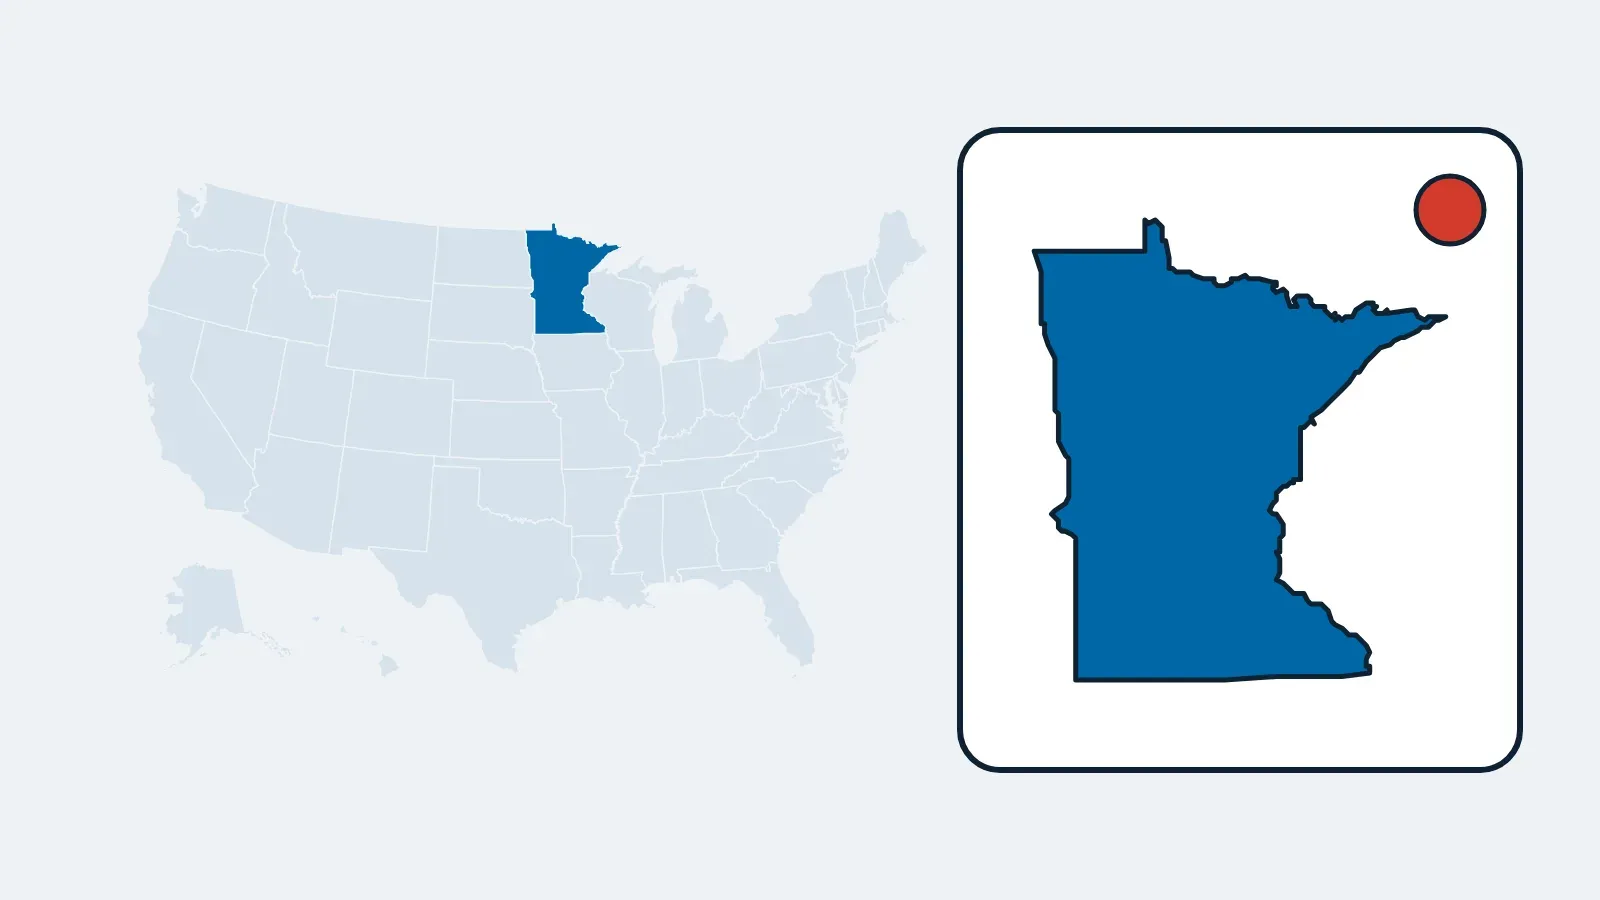
Minnesota policy rules
State schedule- UM coverage rule
- Required
- Minimum liability
- 30/60/10Plus $40,000 no-fault PIP per person
- UM/UIM rule
- Required, 25/50 minimum for both UM and UIMNo rejection allowed
- Insurer cancellation notice
- 30 days; 10 days for nonpayment or in the first 59 daysAfter 60 days, only for reasons listed in section 65B.15
- Nonrenewal notice
- 60 daysMust state the specific reason; not solely for age
- Regulator
- Minnesota Department of Commerce
What every Minnesota policy must include
The Minnesota No-Fault Automobile Insurance Act (chapter 65B of the Minnesota Statutes) sets the floor for each part of the policy. Liability coverage must be at least $30,000 for one injured person, $60,000 for all injuries in one accident, and $10,000 for property damage (section 65B.49, subdivision 3). Many drivers carry more; the limits gap worksheet shows what a larger crash could leave unpaid.
| Coverage | Minimum | Statute |
|---|---|---|
| Bodily injury liability | $30,000 per person / $60,000 per accident | 65B.49, subd. 3 |
| Property damage liability | $10,000 per accident | 65B.49, subd. 3 |
| Personal injury protection | $40,000 per person: $20,000 medical, $20,000 non-medical | 65B.44, subd. 1 |
| Uninsured motorist | $25,000 per person / $50,000 per accident | 65B.49, subd. 3a |
| Underinsured motorist | $25,000 per person / $50,000 per accident | 65B.49, subd. 3a |
The insurance identification card may be electronic. Section 169.791 counts an electronic card as valid proof, and showing it on a phone does not give an officer consent to look at anything else on the device.
No-fault PIP and the UM/UIM requirement
Personal injury protection pays your own losses after a crash regardless of fault. The basic benefit under section 65B.44 is $40,000 per person: $20,000 for medical expense and $20,000 shared among income loss, replacement services, funeral expense and survivors' losses. Read personal injury protection for how the coverage appears on a policy.
Uninsured and underinsured motorist coverage is not a choice in Minnesota. Section 65B.49, subdivision 3a, bars an insurer from issuing or renewing a policy on a car registered or principally garaged in the state unless both coverages are included, and the owner must keep them. There is no rejection form. You can buy higher limits; see Part C for what they pay.
When a Minnesota insurer can cancel your policy
During a new policy's first 59 days, the reason list below does not yet apply and the insurer needs to give only 10 days' notice, and if it acts near the end of that window, coverage runs until 10 days after the notice was mailed. Once the policy has been in force 60 days, and from the start on a renewal, section 65B.15 allows cancellation only for listed reasons. The main ones are:
- Nonpayment of premium.
- A material misrepresentation to get the policy, or a false or fraudulent claim.
- Not disclosing accidents or moving violations from the past 36 months when the application asked, or leaving out other requested rating information.
- Knowingly failing to report a loss or suit, or refusing to cooperate.
- A license suspension or revocation within 36 months for a traffic offense or test refusal, or certain serious driving convictions, for a named insured or regular driver.
- A car that is unsafe, used for hire (car pools and volunteer drivers aside), or changed in a way that substantially raises the risk.
Section 65B.16 sets the notice. For any listed reason other than nonpayment, the insurer must mail or deliver at least 30 days' notice, and the notice must state the specific reason. For nonpayment, 10 days' notice with the reason is enough. The same rules apply when an insurer cuts your liability limits midterm. If you cancel yourself, estimate the return premium with the cancellation refund worksheet.
Renewal and nonrenewal in Minnesota
Under section 65B.17, an insurer must give at least 60 days' notice before it refuses to renew, mailed or delivered to the address on the policy, with the specific reason. If the nonrenewal comes from ending its contract with your agent, the notice has to say so. The 60-day rule does not apply when the insurer has offered to renew or the renewal premium is not paid.
Where to ask and complain
- Read the reason on the notice. Minnesota notices must state the specific reason; ask the insurer in writing if it is unclear.
- Call the Department of Commerce at 651-539-1600, or 800-657-3602 from Greater Minnesota, or use its online complaint form.
- Line up new coverage before the end date. UM, UIM and PIP must continue without a gap; see lapse and reinstatement.
Policyholder questions
Can I drop uninsured motorist coverage in Minnesota?
No. Minnesota requires both uninsured and underinsured motorist coverage on every policy for a car registered or garaged in the state, at least $25,000 per person and $50,000 per accident.
Can a Minnesota insurer cancel my policy after a claim?
A claim alone is not a listed reason once the policy has been in force 60 days. Fraud, nonpayment and certain license or driving-record events are. A claim history can affect renewal, with 60 days' notice.
Can I show my Minnesota insurance card on my phone?
Yes. State law accepts an electronic insurance identification card, and showing it does not let an officer look through the rest of your phone.
Sources
- Minnesota Statutes, Section 65B.49 — Required coverages, liability and UM/UIM minimums
- Minnesota Statutes, Section 65B.15 — Grounds for cancellation
- Minnesota Statutes, Section 65B.16 — Notice of cancellation
- Minnesota Statutes, Section 65B.17 — Nonrenewal
- Minnesota Statutes, Section 65B.44 — Basic economic loss benefits (PIP)
- Minnesota Statutes, Section 169.791 — Insurance identification card, including electronic format
- Minnesota Department of Commerce — Auto Insurance Guide
Facts on this page were checked against these sources on November 15, 2026. Minnesota's 2026 session law changed only a cross-reference in section 65B.15, not the cancellation reasons or notice periods.
Request policy quotes
Answer six questions about the policy you need. PolicyBrook passes the request to licensed insurance agents and insurers who can quote it; you compare and decide.
- The policy you need. Cars, drivers, coverage and ZIP.
- Your contact details and consent to be contacted.
- A licensed insurance agent or insurer contacts you with a quote. Nothing is bound until you sign and pay.
PolicyBrook is not paid by you. The licensed insurance agents and insurers who contact you set their own prices and terms. How we make money.
Related readings
-
Policy part
Uninsured motorists (Part C)
Four kinds of uninsured vehicle, who is insured, limits, 60-day trial right after arbitration, state rules.
-
Policy event
Insurer cancellation
After 60 days, only listed reasons; 10 to 60 days' notice by state, and how to appeal.
-
Policy event
Nonrenewal
Notice periods from 15 to 75 days, reasons states bar, and how to ask the regulator for review.