State: Reject in writing
Kentucky: The Rules Your Auto Policy Must Follow
Kentucky is a choice no-fault state. Your policy carries personal injury protection unless you formally reject the limit on your right to sue, uninsured motorist coverage stays on unless you reject it in writing, and the law sets long notice periods for nonrenewal.
By PolicyBrook Editorial Team Updated 4-minute read
Declarations
Kentucky- UM/UIM rule
- Reject in writing
- Minimum liability
- 25/50/25
- Insurer cancellation notice
- 20 days (14 nonpayment)
- Nonrenewal notice
- 75 days
In brief
A Kentucky policy must carry at least $25,000/$50,000/$25,000 of liability coverage, or a $60,000 single limit, plus $10,000 of personal injury protection. Uninsured motorist coverage is included unless a named insured rejects it in writing. After 60 days in force, an insurer may cancel only for reasons listed in KRS 304.20-040, with 20 days' notice, or 14 days for nonpayment. A company that will not renew must give 75 days' notice. The Kentucky Department of Insurance enforces these rules.
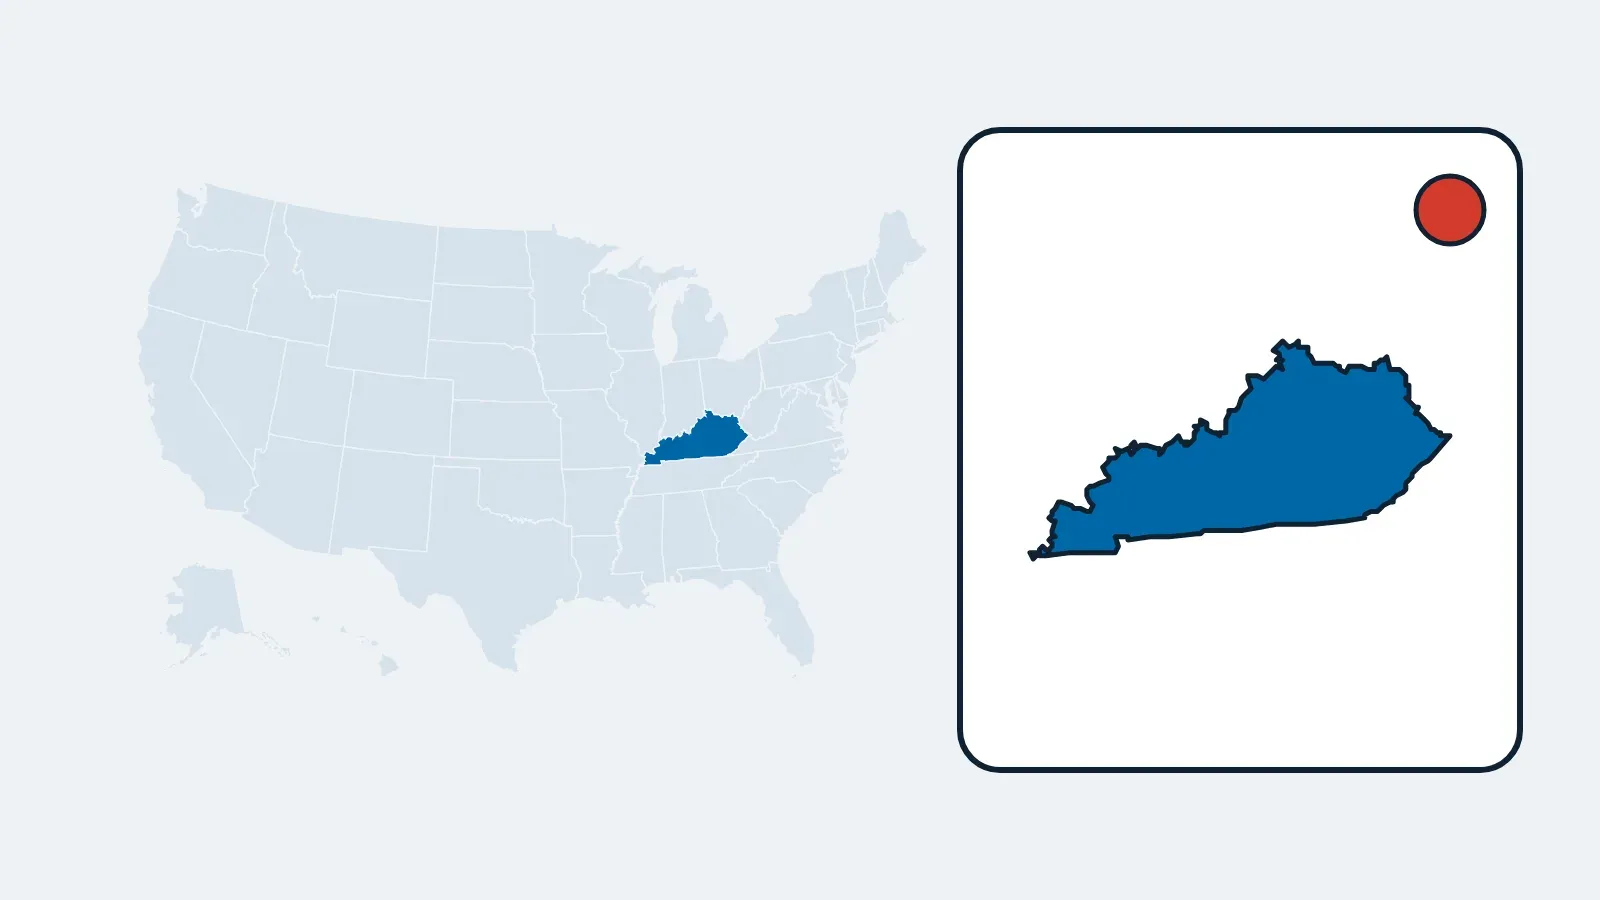
Kentucky policy rules
State schedule- UM coverage rule
- Reject in writing
- Minimum liability
- 25/50/25 or $60,000 single limitPlus $10,000 PIP unless the no-fault limits are rejected
- UM/UIM rule
- Included unless rejected in writingUIM must be available on request (KRS 304.20-020; DOI checklist)
- Insurer cancellation notice
- 20 days; 14 days for nonpayment or in the first 60 daysAfter 60 days, only for reasons in KRS 304.20-040
- Nonrenewal notice
- 75 daysMissed notice means the policy is treated as renewed
- Regulator
- Kentucky Department of Insurance
Minimum limits and no-fault coverage
The Kentucky Department of Insurance's personal auto review checklist lists the required liability as $25,000 per person and $50,000 per accident for bodily injury plus $25,000 for property damage, or a $60,000 combined single limit. These are floors for Part A; the limits gap worksheet shows what a larger claim could leave uncovered.
Every policy also carries basic reparation benefits, Kentucky's name for personal injury protection (PIP), of at least $10,000 per person. The department's no-fault rejection form (version 9/22) describes what it pays: medical expenses, lost wages up to $200 a week, replacement services and survivors' benefits. Insurers must make added reparation benefits, meaning higher PIP, available on request. See personal injury protection for how the coverage reads in a policy.
Uninsured motorist coverage stays on unless you reject it in writing
KRS 304.20-020 requires an auto liability policy for a vehicle registered or principally garaged in Kentucky to include uninsured motorist coverage at no less than the KRS 304.39-110 bodily injury limits. A named insured may reject it in writing, and the rejection applies to everyone insured under the policy.
The rejection carries forward to renewal, replacement and amended policies from the same insurer or its affiliates. The coverage returns only if a named insured asks for it in writing. The department's checklist tells insurers to make underinsured motorist coverage available on request even when UM has been rejected. See Part C for what UM pays.
When a Kentucky insurer can cancel your policy
KRS 304.20-040 covers policies issued to one person or to a married couple in the same household for private passenger cars and light four-wheel vehicles not used in business. Assigned risk plan policies and garage or service-station policies are outside it.
During the first 60 days, a new policy can be cancelled for any reason, with at least 14 days' notice. After that, and for renewals, cancellation is allowed only for:
- Nonpayment of premium.
- Suspension or revocation of the license or registration of the named insured or another regular driver.
- Fraud or material misrepresentation.
- Willful acts or omissions that increase the insured hazard.
- A finding by the commissioner that keeping the policy would violate the insurance code or its rules.
The insurer must mail or deliver notice at least 20 days before the cancellation date, or at least 14 days when the reason is nonpayment, and the reason must come with the notice. Proof of mailing to the address in the policy counts as proof of notice. When the reason is not nonpayment, the notice must also mention the Kentucky automobile assigned risk plan and your right to ask the commissioner, within 7 days, to review the cancellation. The statute does not set a refund method, so check your policy's cancellation clause; the cancellation refund worksheet helps you check the amount.
Renewal and nonrenewal in Kentucky
An insurer that does not plan to renew must give at least 75 days' advance notice, with the reason. If it fails to, the policy is treated as renewed on the same terms, as long as you pay the premium. The same 7-day review request applies.
Renewal billing has its own rule. If the insurer sends a renewal notice showing the premium and due date at least 30 days before the term ends and you do not pay, the policy ends on the due date. The insurer must then tell you within 15 days that the policy was not renewed.
Where to ask and complain
- Read the notice. Check the reason, the mailing date and the effective date against KRS 304.20-040.
- Request a review within 7 days if the notice offers one and you disagree with the reason.
- Contact the Kentucky Department of Insurance at 800-595-6053 or file a complaint through insurance.ky.gov.
- Arrange replacement coverage before the end date; see lapse and reinstatement.
Policyholder questions
Is PIP mandatory in Kentucky?
PIP of at least $10,000 per person comes with every policy. The only way out is to formally reject the no-fault limits on lawsuits, which also gives up PIP unless you buy it back.
How do I reject uninsured motorist coverage in Kentucky?
A named insured signs a written rejection. It carries to later policies with the same insurer until a named insured asks in writing to restore the coverage. Read Part C first.
What happens if my Kentucky insurer misses the 75-day nonrenewal notice?
Under KRS 304.20-040, the policy is treated as renewed on the same terms, subject to paying the premium. See nonrenewal for the general steps.
Sources
- KRS 304.20-040 — Cancellation and nonrenewal of automobile insurance
- KRS 304.20-020 — Uninsured vehicle coverage
- Kentucky Department of Insurance — Personal auto review requirements checklist (3rd edition, rev. 03/2019)
- Kentucky Department of Insurance — No-fault rejection form NF 1 (9/22)
- Kentucky Department of Insurance
Facts on this page were checked against these sources on November 15, 2026. The liability and PIP minimums come from the Department of Insurance's checklist and rejection form; KRS 304.39-110 was not opened for this check.
Request policy quotes
Answer six questions about the policy you need. PolicyBrook passes the request to licensed insurance agents and insurers who can quote it; you compare and decide.
- The policy you need. Cars, drivers, coverage and ZIP.
- Your contact details and consent to be contacted.
- A licensed insurance agent or insurer contacts you with a quote. Nothing is bound until you sign and pay.
PolicyBrook is not paid by you. The licensed insurance agents and insurers who contact you set their own prices and terms. How we make money.
Related readings
-
Policy event
Nonrenewal
Notice periods from 15 to 75 days, reasons states bar, and how to ask the regulator for review.
-
Endorsement
Personal injury protection
No-fault injury coverage: $10,000 required in Florida, rejectable in Texas, offered in Washington.
-
Policy part
Uninsured motorists (Part C)
Four kinds of uninsured vehicle, who is insured, limits, 60-day trial right after arbitration, state rules.