State: Required
West Virginia: The Rules Your Auto Policy Must Follow
West Virginia requires uninsured motorist coverage on every policy, makes insurers offer more, lists the only reasons a settled policy can be cancelled, and adds extra protection once a policy has been with the same company for two years.
By PolicyBrook Editorial Team Updated 6-minute read
Declarations
West Virginia- UM/UIM rule
- Required
- Minimum liability
- 25/50/25
- Insurer cancellation notice
- 30 days (14 nonpayment)
- Nonrenewal notice
- 45 days
In brief
A West Virginia policy must carry at least $25,000/$50,000/$25,000 of liability coverage and uninsured motorist coverage at no less than those limits; higher UM limits and underinsured motorist coverage must be offered. After 60 days, an insurer can cancel only for reasons listed in W. Va. Code §33-6A-1, with 30 days' notice (14 days for nonpayment). Nonrenewal needs 45 days' notice, and after two years only listed reasons apply. The West Virginia Offices of the Insurance Commissioner enforces these rules.
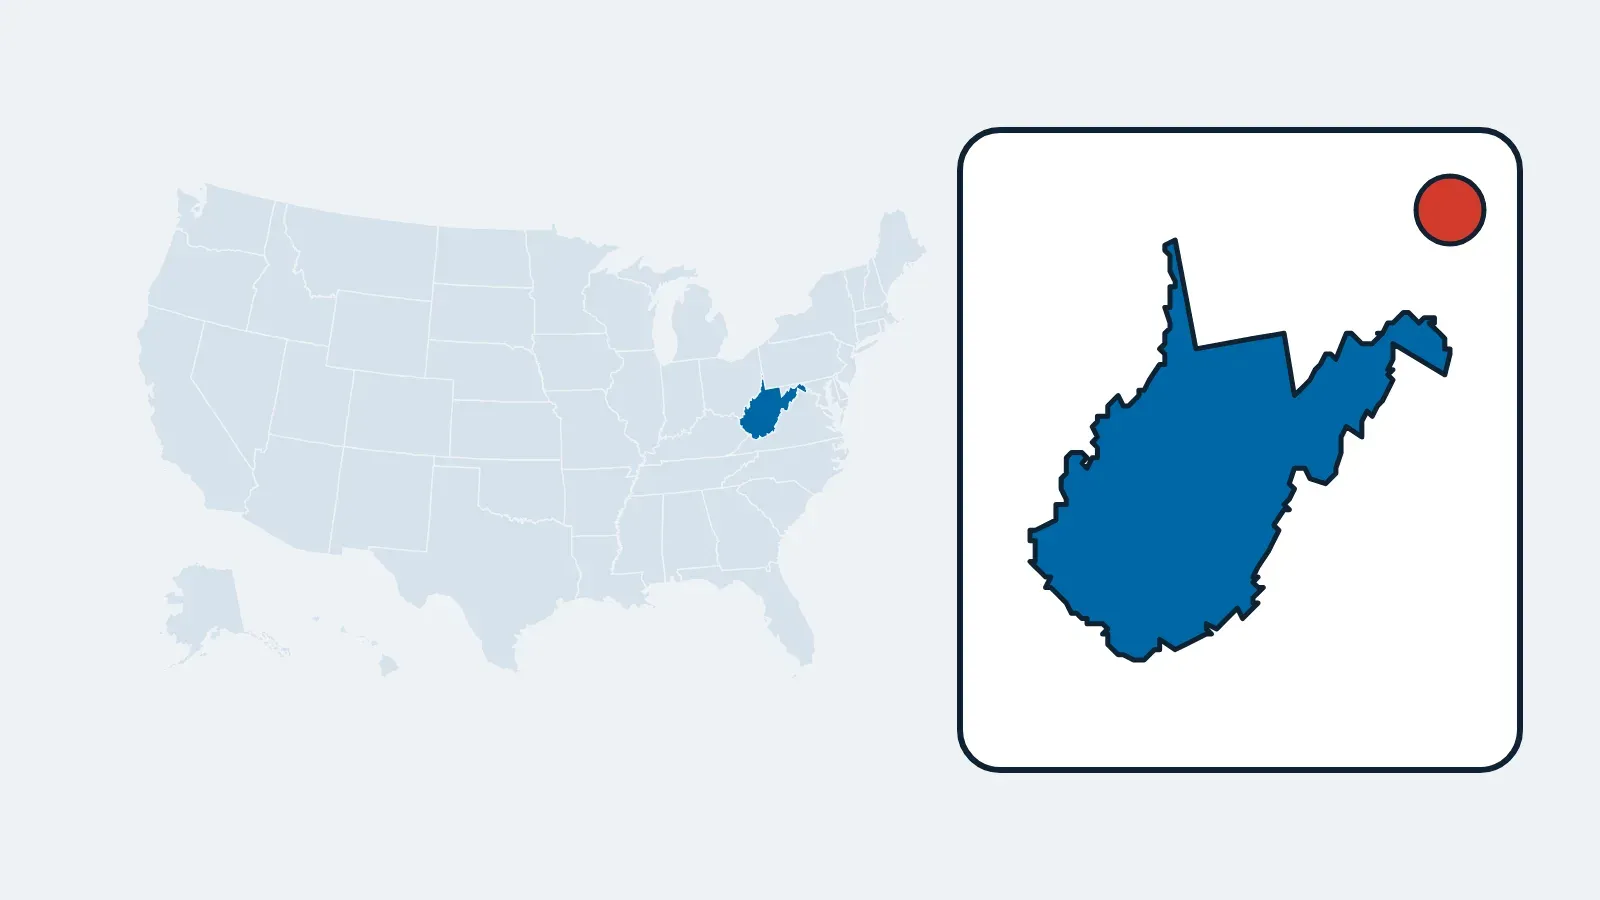
West Virginia policy rules
State schedule- UM coverage rule
- Required
- Minimum liability
- 25/50/25
- UM/UIM rule
- UM required at the 25/50/25 minimumHigher UM limits and underinsured motorist coverage must be offered
- Insurer cancellation notice
- 30 days; 14 days for nonpaymentAfter 60 days, only for reasons listed in §33-6A-1
- Nonrenewal notice
- 45 daysAfter two years in force, only for listed reasons; hearing available
- Regulator
- West Virginia Offices of the Insurance Commissioner
Minimum limits and proof in West Virginia
W. Va. Code §17D-4-2 has required 25/50/25 since January 1, 2016: $25,000 for one person's injuries, $50,000 for all injuries in one accident, and $25,000 for property damage. Before that the floor was 20/40/10. Compare the minimum with the cost of a serious crash using the limits gap worksheet.
Since a 2015 amendment, §17D-2A-4 counts an image of your insurance card displayed on a phone or similar wireless device as proof of insurance, as long as the image comes from your insurer and shows the required information.
UM is required; more must be offered
Under §33-6-31(b), a liability policy must include uninsured motorist coverage with limits no less than the §17D-4-2 minimums. The statute contains no way to reject that required layer.
- Higher UM limits: the policy must give you the option to buy up to $100,000 per person, $300,000 per accident and $50,000 for property damage.
- Underinsured motorist coverage: must be offered up to your own liability limits, and it pays without a set-off against other policies.
- Property damage deductible: the policy may exclude the first $300 of property damage caused by an uninsured driver.
Read Part C to see how these layers show on your declarations page.
When a West Virginia insurer can cancel your policy
Under §33-6A-1, once a private passenger policy has been in effect 60 days, or right away for a renewal, the insurer may cancel during the term only for these reasons:
- Nonpayment of the premium or an installment.
- Material misrepresentation to get the policy, or a violation of its material terms.
- A suspended or revoked license for the named insured or a regular household or customary driver, including for refusing a chemical test.
- A driver with epilepsy or heart attacks who cannot get a physician's certificate of fitness to drive.
- Certain convictions during the policy period: a felony or assault involving a vehicle, impaired driving, leaving the scene, vehicle theft, false statements on a license application, or three or more moving violations in 12 months that each carried at least 3 points.
The notice must give the effective date and the specific reason, and it must arrive by first-class mail, or electronically if you asked for that. It must allow at least 30 days, or 14 days for nonpayment counted from the mailing date; a valid payment mailed first class before the period ends counts as paid. If you never pay the first premium on a new policy, the policy is voidable from the start after a 10-day written warning.
Nonrenewal and the two-year protection
Section 33-6A-4 requires at least 45 days' notice before an insurer declines to renew. Once a policy has been in force two consecutive years or longer, nonrenewal is allowed only for listed reasons. These track the cancellation reasons and add a few more, such as two or more qualifying moving violations in 12 months, a second at-fault accident in 12 months, or the insurer's approved withdrawal from the state.
- Read the reason and the date. Check them against §33-6A-1 or §33-6A-4.
- Ask for a hearing before the Insurance Commissioner if you think the reason is wrong; the notice explains how.
- Shop before the end date so your coverage does not lapse; see nonrenewal for the steps in order.
Policyholder questions
Can I reject uninsured motorist coverage in West Virginia?
Not the required layer. Every policy must include UM at no less than 25/50/25. Higher UM limits and underinsured motorist coverage are options the insurer must offer.
How much notice does a West Virginia insurer give before cancelling?
At least 30 days, or 14 days for nonpayment. After 60 days, only the reasons in §33-6A-1 allow a midterm cancellation.
Can I show my West Virginia insurance card on my phone?
Yes. An image of the card on a wireless device counts as proof if it comes from your insurer and shows the required details.
Sources
- W. Va. Code §33-6A-1 — Cancellation prohibited except for specified reasons; notice
- W. Va. Code §33-6A-4 — Advance notice of nonrenewal; reasons; hearing
- W. Va. Code §33-6-31 — Uninsured and underinsured motorist coverage
- W. Va. Code §17D-4-2 — Minimum liability limits
- West Virginia Legislature — Enrolled SB 373 (2015), image of proof of insurance on a wireless device
- West Virginia Offices of the Insurance Commissioner — Cancellation of auto insurance
Facts on this page were checked against these sources on November 15, 2026. The Commissioner's consumer page gives 30 days' notice without the shorter nonpayment period; the 14-day nonpayment rule comes from §33-6A-1.
Request policy quotes
Answer six questions about the policy you need. PolicyBrook passes the request to licensed insurance agents and insurers who can quote it; you compare and decide.
- The policy you need. Cars, drivers, coverage and ZIP.
- Your contact details and consent to be contacted.
- A licensed insurance agent or insurer contacts you with a quote. Nothing is bound until you sign and pay.
PolicyBrook is not paid by you. The licensed insurance agents and insurers who contact you set their own prices and terms. How we make money.
Related readings
-
Policy event
Insurer cancellation
After 60 days, only listed reasons; 10 to 60 days' notice by state, and how to appeal.
-
Policy event
Nonrenewal
Notice periods from 15 to 75 days, reasons states bar, and how to ask the regulator for review.
-
Policy part
Uninsured motorists (Part C)
Four kinds of uninsured vehicle, who is insured, limits, 60-day trial right after arbitration, state rules.