State: Reject in writing
Arizona: The Rules Your Auto Policy Must Follow
Arizona sets the minimum limits, makes insurers offer uninsured and underinsured motorist coverage in writing, and lists the only reasons a company can cancel once a policy has run 60 days. Here is what each rule means for your policy.
By PolicyBrook Editorial Team Updated 5-minute read
Declarations
Arizona- UM/UIM rule
- Written offer; may decline
- Minimum liability
- 25/50/15
- Insurer cancellation notice
- 10 days
- Nonrenewal notice
- 45 days
In brief
An Arizona policy issued or renewed since July 1, 2020 must carry at least $25,000/$50,000/$15,000 of liability coverage. Insurers must offer uninsured and underinsured motorist coverage by written notice on a form the state approves; you may decline it. After a policy has run 60 days, an insurer can cancel only for listed reasons, with at least 10 days' notice, and it must give 45 days' notice before it declines to renew. The Arizona Department of Insurance and Financial Institutions oversees these rules.
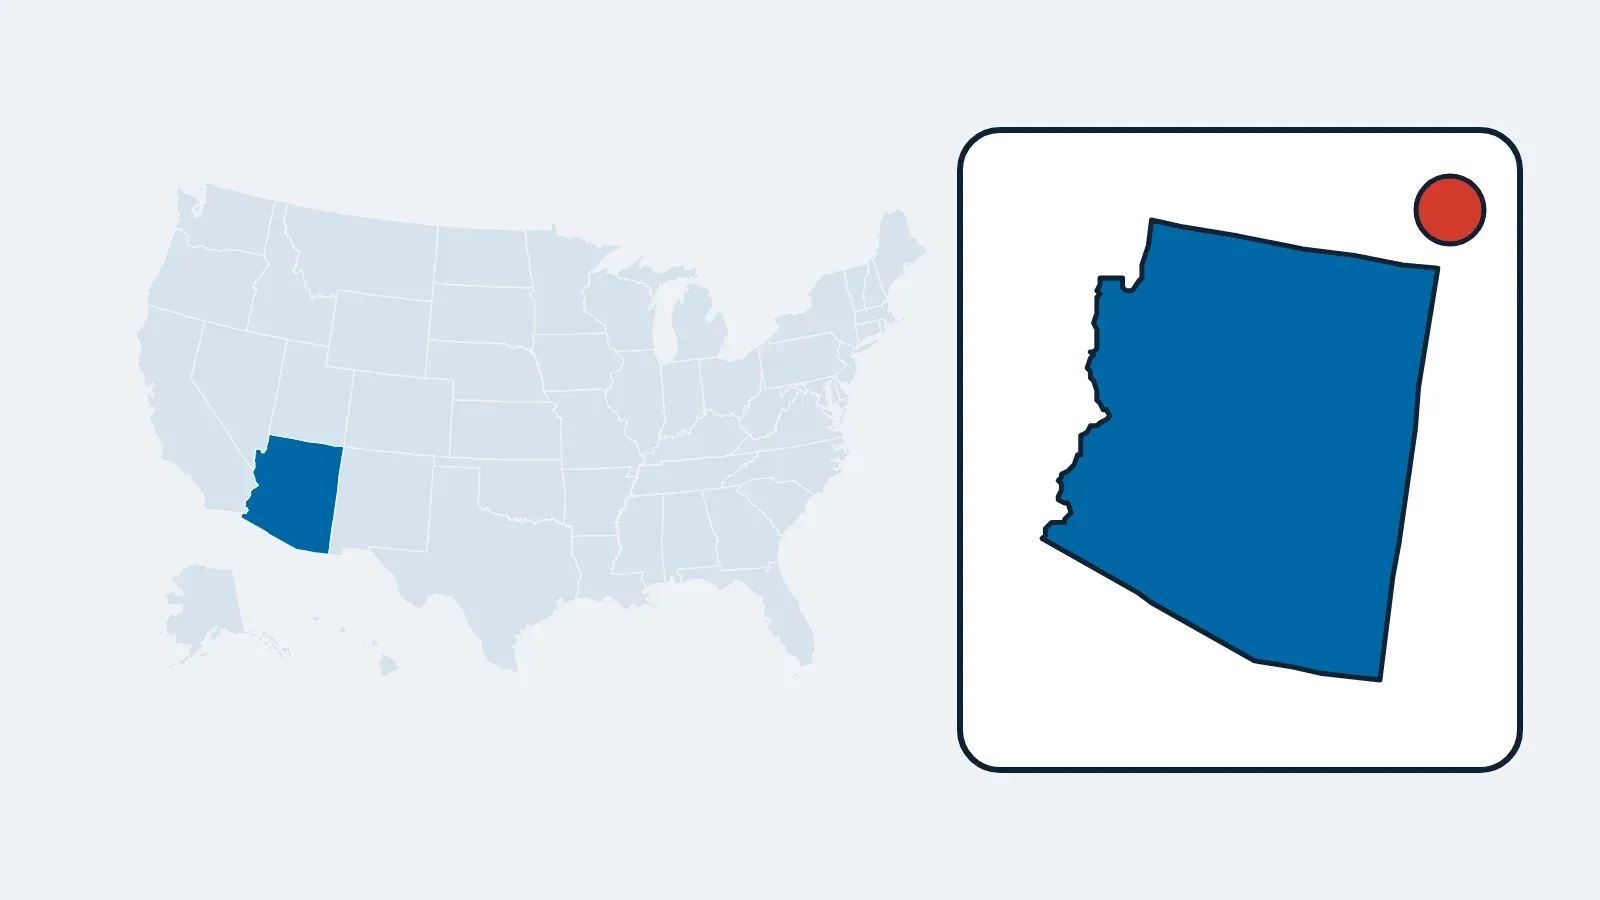
Arizona policy rules
State schedule- UM coverage rule
- Reject in writing
- Minimum liability
- 25/50/15For policies issued or renewed on or after July 1, 2020
- UM/UIM rule
- Must be offered in writing on an approved form; you may declineThe declarations page records the choice; no new offer needed at renewal
- Insurer cancellation notice
- 10 daysAfter 60 days in force, only for reasons in §20-1631(D)
- Nonrenewal notice
- 45 daysFor reasons other than nonpayment; notice must state facts and the right to complain
- Regulator
- Arizona Department of Insurance and Financial Institutions
Minimum limits on an Arizona policy
Section 28-4009 of the Arizona Revised Statutes sets the minimum for policies issued or renewed on or after July 1, 2020: $25,000 for injuries to one person, $50,000 for all injuries in one accident and $15,000 for property damage. Policies issued or renewed before that date could carry 15/30/10. Any policy renewed since then has moved to the higher floor. If you want to see how far these limits reach in a larger crash, try the limits gap worksheet.
You may show proof of coverage on a phone. Under Section 28-4135(B), the evidence of financial responsibility may be displayed on a wireless device in the car, and showing it does not give an officer consent to look at anything else on the device.
UM and UIM must be offered in writing
Arizona does not force you to buy uninsured (UM) or underinsured (UIM) motorist coverage, but Section 20-259.01 makes the insurer offer both by written notice, using a form approved by the director. A producer who uses that form has met the standard for offering and explaining the coverage.
Your choice shows on the declarations page. The statute treats the declarations page sent to the named insured as the final record of whether you bought or rejected each coverage. The insurer does not have to make a new offer when the policy renews, is reinstated after a lapse, or is changed or replaced.
| Coverage | Limits you can buy | If you do not want it |
|---|---|---|
| Uninsured motorist | Up to your bodily injury liability limits, not below the 28-4009 minimum | Decline it on the approved offer form |
| Underinsured motorist | Any amount you authorize up to your bodily injury liability limits | Decline it on the approved offer form |
See Part C for what each coverage pays and who it protects.
When an Arizona insurer can cancel your policy
Section 20-1631(D) limits cancellation once a policy has been in effect 60 days, and from the start of any renewal. After that point, the reasons are:
- You do not pay the premium when it is due.
- The insurance was obtained through fraudulent misrepresentation.
- The named insured or a regular household or frequent driver has a license suspended or revoked, has a permanent disability without a medical certificate of ability to drive, or has certain convictions, such as reckless driving, leaving the scene or driving under the influence.
- A car rated as a private passenger vehicle is used regularly and frequently for commercial purposes, or for transportation network services without the needed coverage.
- The insurer is in rehabilitation or receivership, or the director finds that continuing the policy would break state law or endanger the insurer's solvency.
Section 20-1632 requires at least 10 days' notice before a cancellation takes effect. The notice must state the specific facts behind the decision and tell you that you may complain to the director within 10 days after you receive it. It must also tell you about the state's assigned risk plan. A notice that does not follow these rules does not cancel the policy.
The unearned premium generally goes back to you with the notice, or separately, so that both arrive at least 10 days before the effective date. The refund can be paid electronically if you set up electronic payments with the insurer. Estimate the amount with the cancellation refund worksheet.
Renewal and nonrenewal in Arizona
When an Arizona insurer decides not to renew for a reason other than unpaid premium, Section 20-1632 requires it to send the notice at least 45 days before the nonrenewal takes effect. The same content rules apply: the specific facts, your right to complain to the director within 10 days, and a note about the assigned risk plan.
Where to ask and complain
- Read the stated facts. An Arizona notice must say why the insurer is acting.
- Complain within 10 days. The notice gives you the right to complain to the director of the Arizona Department of Insurance and Financial Institutions within 10 days after you receive it.
- Line up new coverage before the end date. See lapse and reinstatement for what a gap can cost.
Policyholder questions
Can an Arizona insurer cancel my policy after a claim?
Not for a claim alone once the policy has run 60 days. After that point, cancellation is limited to reasons such as unpaid premium, fraud, a suspended license, certain convictions or regular commercial use.
Do I have to buy uninsured motorist coverage in Arizona?
No. The insurer must offer UM and UIM in writing on an approved form, and you may decline. Your declarations page records the choice. See Part C.
Can I show my Arizona insurance card on my phone?
Yes. Arizona law lets you display proof of financial responsibility on a wireless device in the car, and doing so does not let the officer search other content on it.
Sources
- Arizona Revised Statutes §20-1631 — Cancellation of automobile policies
- Arizona Revised Statutes §20-1632 — Notice of cancellation and nonrenewal
- Arizona Revised Statutes §20-259.01 — Uninsured and underinsured motorist coverage
- Arizona Revised Statutes §28-4009 — Minimum liability limits
- Arizona Revised Statutes §28-4135 — Evidence of financial responsibility on a wireless device
- Arizona Department of Insurance and Financial Institutions
Facts on this page were checked against these sources on November 15, 2026. Arizona raised its minimum limits from 15/30/10 to 25/50/15 for policies issued or renewed on or after July 1, 2020.
Request policy quotes
Answer six questions about the policy you need. PolicyBrook passes the request to licensed insurance agents and insurers who can quote it; you compare and decide.
- The policy you need. Cars, drivers, coverage and ZIP.
- Your contact details and consent to be contacted.
- A licensed insurance agent or insurer contacts you with a quote. Nothing is bound until you sign and pay.
PolicyBrook is not paid by you. The licensed insurance agents and insurers who contact you set their own prices and terms. How we make money.
Related readings
-
Policy event
Insurer cancellation
After 60 days, only listed reasons; 10 to 60 days' notice by state, and how to appeal.
-
Policy event
Nonrenewal
Notice periods from 15 to 75 days, reasons states bar, and how to ask the regulator for review.
-
Policy part
Uninsured motorists (Part C)
Four kinds of uninsured vehicle, who is insured, limits, 60-day trial right after arbitration, state rules.